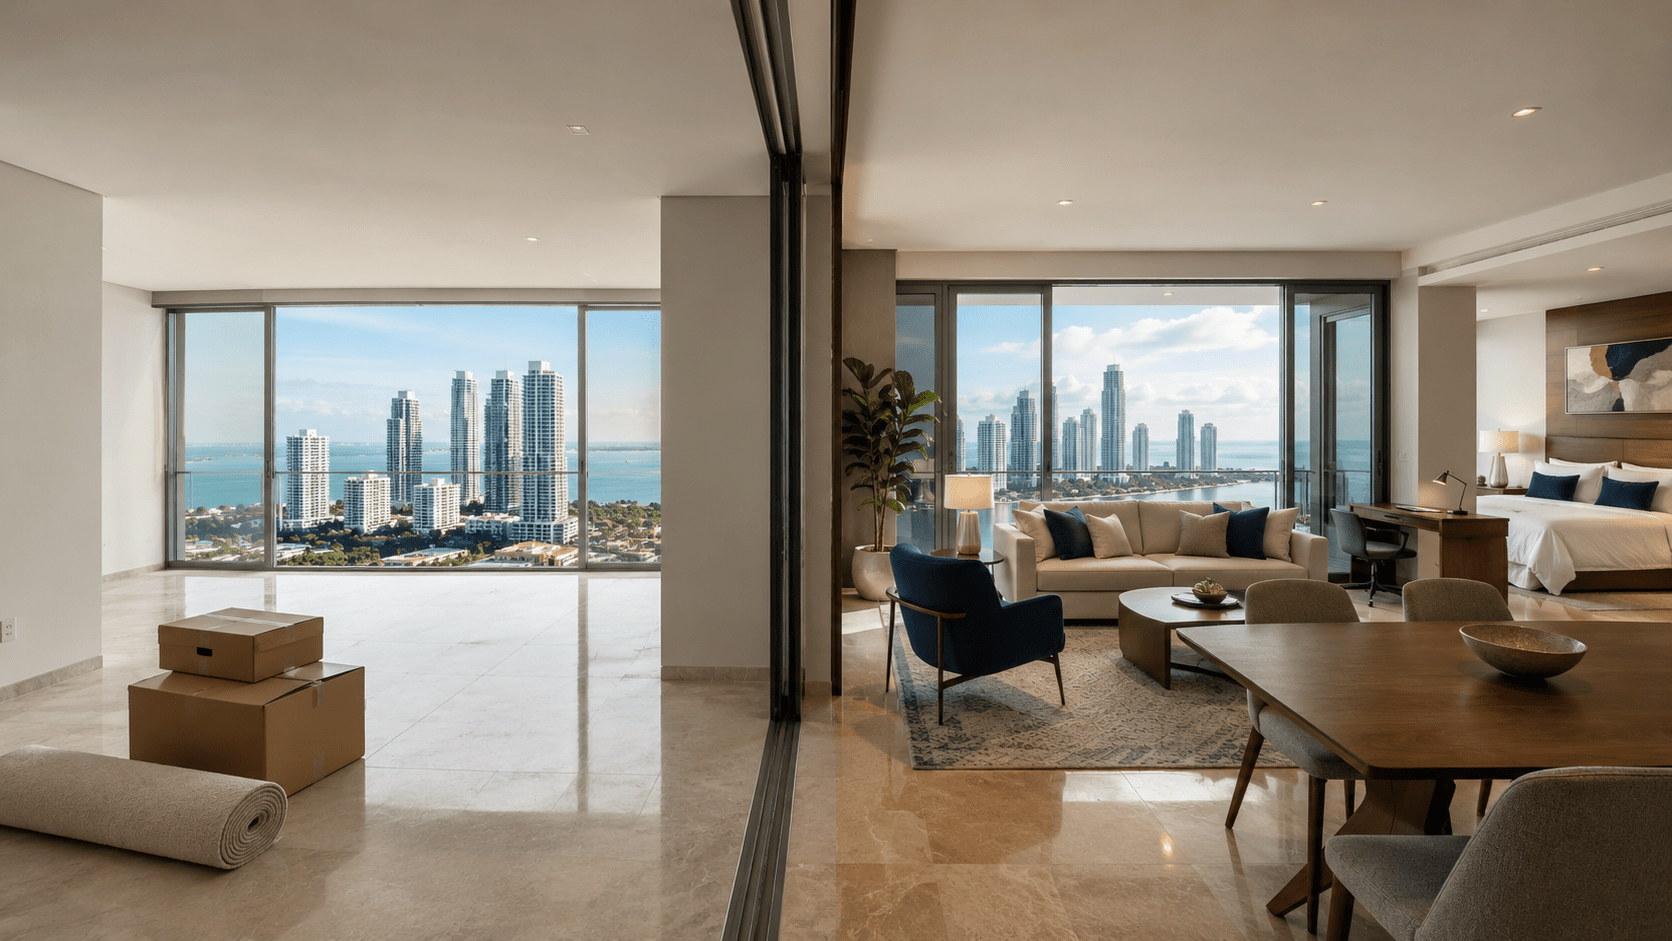
Many investors no longer want to buy an empty unit, manage renovations, source furniture, recruit vendors, set rents, and supervise tenants from another country. They want a property prepared for its intended rental strategy and backed by professional operations.
That shift explains the interest behind turnkey rental property growth. It does not mean every turnkey asset earns more than every traditional rental. No standardized global dataset compares the categories. The defensible thesis is that ready-to-operate properties fit demand for managed housing, business mobility, cross-border ownership, and operating expertise.
Turnkey properties are gaining ground because they shorten the path from purchase to rental operations and let investors delegate pricing, distribution, maintenance, and guest service. Capital flows into professionally managed living assets and resilient travel demand support the trend, but no global dataset proves universal outperformance over traditional rentals.
Turnkey Rental Property Growth: What the Data Shows
“Turnkey” is not a consistently reported sector. It can mean a renovated house with a tenant, a furnished apartment ready for bookings, or a fully managed asset. Traditional rental is equally broad.
For the underlying definition, see what a turnkey investment property includes.
Claims that turnkey properties are globally outperforming traditional rentals therefore require caution. Available evidence measures adjacent trends rather than a universal yield contest.
Managed rental investment trends in 2026 must therefore be read across living-sector capital, travel demand, and local operating data.
JLL’s 2025 Global Living Investment Universe forecast $1.4 trillion in living-sector transactions over the following five years, 14% above the 2015–2019 level. Cross-border purchases represented one-quarter of living investment in the preceding five years. These figures include several residential formats but show appetite for living assets and operating platforms.
The Global Business Travel Association’s 2026 outlook forecast $1.71 trillion in global business travel spending and 1.84 billion work trips in 2026. Spending was expected to rise 7.2%, but trip volume only 1.3%, partly due to higher travel costs. This indicates active mobility, not guaranteed rental demand.
Macro data can validate a theme. Only local operating data can validate an asset.
Why the Managed Turnkey Model Is Gaining Attention
A shorter path to revenue
A conventional purchase may need repairs, furnishing, photography, licensing, channel setup, and tenant or guest acquisition. A genuine turnkey model coordinates those steps before or alongside the acquisition.
That can reduce non-income-producing time and clarify the all-in budget. The advantage disappears if the price hides inflated costs or unsupported forecasts.
Revenue management instead of rent collection alone
Traditional long-term rentals generally use a fixed monthly lease. Professionally managed furnished rentals can adjust rates by season and stay length, distribute inventory across suitable channels, serve corporate accounts, and track:
- Occupancy: Share of available nights sold
- Average daily rate (ADR): Revenue per occupied night
- Revenue per available room (RevPAR): ADR multiplied by occupancy
- Average length of stay (ALOS): Occupied nights divided by completed stays
- Net operating income (NOI): Revenue after normal operating expenses, before financing, income tax, and depreciation
These tools can improve decisions, but management cannot create demand where none exists. The property still needs the right location, renter profile, price, rules, and competitive position.
This operating shift is explored further in Airbnb vs. managed corporate rentals.
More workable remote ownership
A local team can handle pricing, occupant service, maintenance, and reporting. The owner still reviews results, approves major spending, maintains reserves, and decides when to sell. “Hands-off” means delegated daily operations, not zero oversight.
Turnkey Property vs. Traditional Rental
Here, “turnkey” means a furnished, ready-to-operate property with professional management. “Traditional rental” means an unfurnished property on a conventional long-term lease. Actual structures vary.
| Factor | Managed turnkey property | Traditional rental |
|---|---|---|
| Readiness | Prepared for its rental strategy | May need repairs or leasing work |
| Revenue start | Potentially faster; never guaranteed | After setup and tenant placement |
| Pricing | Can vary by demand and stay length | Usually fixed for the lease term |
| Demand | Corporate, relocation, extended stay, leisure | Mainly local residential tenants |
| Owner workload | Lower with full management | Higher if self-managed |
| Operating costs | Management, utilities, furnishing, cleaning, channels | Often lower service and turnover costs |
| Main risk | Premium pricing and operator execution | Setup, vacancy, and owner execution |
Neither model wins automatically. Compare net income after all costs, owner time, and the risks required to produce that income.
Why Latin America Is a Selective Turnkey Opportunity
Latin America is not one market. Laws, currencies, financing, rental rules, infrastructure, and demand differ across countries and cities. Still, selected urban markets have multiple demand drivers.
GBTA’s 2026 forecast said the Americas were benefiting from stronger growth and identified Brazil and greater stability in Argentina as regional drivers. UN Tourism reported in 2026 that international arrivals grew 4% in 2025. These indicators support mobility; they do not forecast one apartment’s occupancy.
Panama shows why local analysis matters. The World Bank’s January 2026 regional outlook forecast 4.1% economic growth for Panama in 2026, driven by finance, business, and logistics services. Those sectors can support corporate-housing and relocation demand. Investors must still test the neighborhood, competing supply, achievable rates, seasonality, building restrictions, and costs.
Investors researching the country can review Panama investment opportunities.
The defensible thesis is not “buy anywhere because the region is growing.” It is “select cities where several demand sources meet professional operations and sound property economics.”
Does the Operating Advantage Reach Net Income?
Higher gross revenue does not ensure a higher net yield. A managed furnished property may pay for utilities, booking commissions, housekeeping, furniture replacement, and active management. Extra revenue must exceed those costs.
Consider this hypothetical comparison. It is not a CS Realty forecast or guaranteed result.
| Annual assumption | Traditional lease | Managed furnished rental |
|---|---|---|
| Gross revenue | $24,000 | To be calculated |
| Operating costs and reserves | $6,000 | $14,000 |
| NOI target | $18,000 | More than $18,000 |
The managed rental must generate more than $32,000 annually to beat the traditional rental’s $18,000 NOI:
Required gross revenue = $18,000 target NOI + $14,000 operating costs
At an assumed $130 ADR, break-even occupancy is:
$32,000 ÷ ($130 × 365) = 67.4%
At 70% occupancy, gross revenue would be $33,215 and NOI $19,215. The advantage would be only $1,215 before financing, income tax, depreciation, currency movement, and selling costs. A modest change in rate or occupancy could remove it.
Investors need base, downside, and break-even cases. Operational sophistication matters only when it produces durable net income after all costs.
Risks and Due-Diligence Questions
Turnkey ownership replaces some setup risk with provider and operator risk. Ask:
- What is included? Get the inventory, completion standard, launch plan, warranties, and service scope in writing.
- Is there a premium? Compare the price with independent sales evidence and realistic self-setup costs.
- What supports the forecast? Request comparable ADR, occupancy, ALOS, monthly seasonality, and expenses.
- How is the operator paid? Review fees, commissions, markups, reserves, reporting, spending authority, and termination rights.
- Can the strategy operate legally? Verify title, foreign-ownership rules, rental permissions, taxes, building bylaws, and insurance with qualified local advisers.
- What weakens the case? Stress-test vacancy, rate cuts, currency moves, maintenance, replacement costs, regulation, and financing.
- Who will buy later? Assess resale liquidity to investors and owner-occupiers.
Transparent assumptions and regular reporting are part of the investment product.
Conclusion: Treat Growth as a Thesis to Test
The evidence behind turnkey rental property growth is strongest as an adoption and operating-model thesis. Managed living assets are attracting capital, travel remains active, and cross-border buyers value local execution. These forces may favor selected Latin American markets.
They do not guarantee superior yield. Results depend on entry price, demand, regulation, cost control, operator quality, and exit strategy. CS Realty’s role as an asset manager, investment platform, and hospitality-grade operator is to align property selection, furnishing, revenue management, maintenance, guest service, and reporting around a defined income strategy.
Ready to test a market with property-level assumptions?
Schedule a Market Briefing Call with CS Realty.
Frequently Asked Questions
What is driving turnkey rental property growth?
Faster rental readiness, lower owner workload, professional operations, cross-border ownership, and investor interest in managed living assets are key drivers. They support adoption but do not prove universal outperformance.
Are turnkey properties more profitable than traditional rentals?
Not automatically. A turnkey asset may launch faster or earn more gross revenue, but it may also carry a premium and higher costs. Compare NOI, net yield, owner time, and downside risk.
What is the difference between a turnkey and traditional rental?
A turnkey rental is prepared for its intended strategy and may include furnishing, occupant acquisition, and management. A traditional purchase may require the owner to complete setup and operations after closing.
Which metrics matter for a managed furnished rental?
Track occupancy, ADR, RevPAR, ALOS, gross revenue, operating costs, NOI, net yield, reserves, and cash flow. Review monthly data so annual averages do not hide seasonality.
Is Latin America a good market for turnkey rental property?
Selected cities may benefit from business, logistics, relocation, tourism, medical, or education demand. Investors must verify local laws, currency exposure, costs, demand, operator quality, and exit liquidity.